By Len Tannenbaum & Adam Tannenbaum
Comfort doesn’t mean alpha
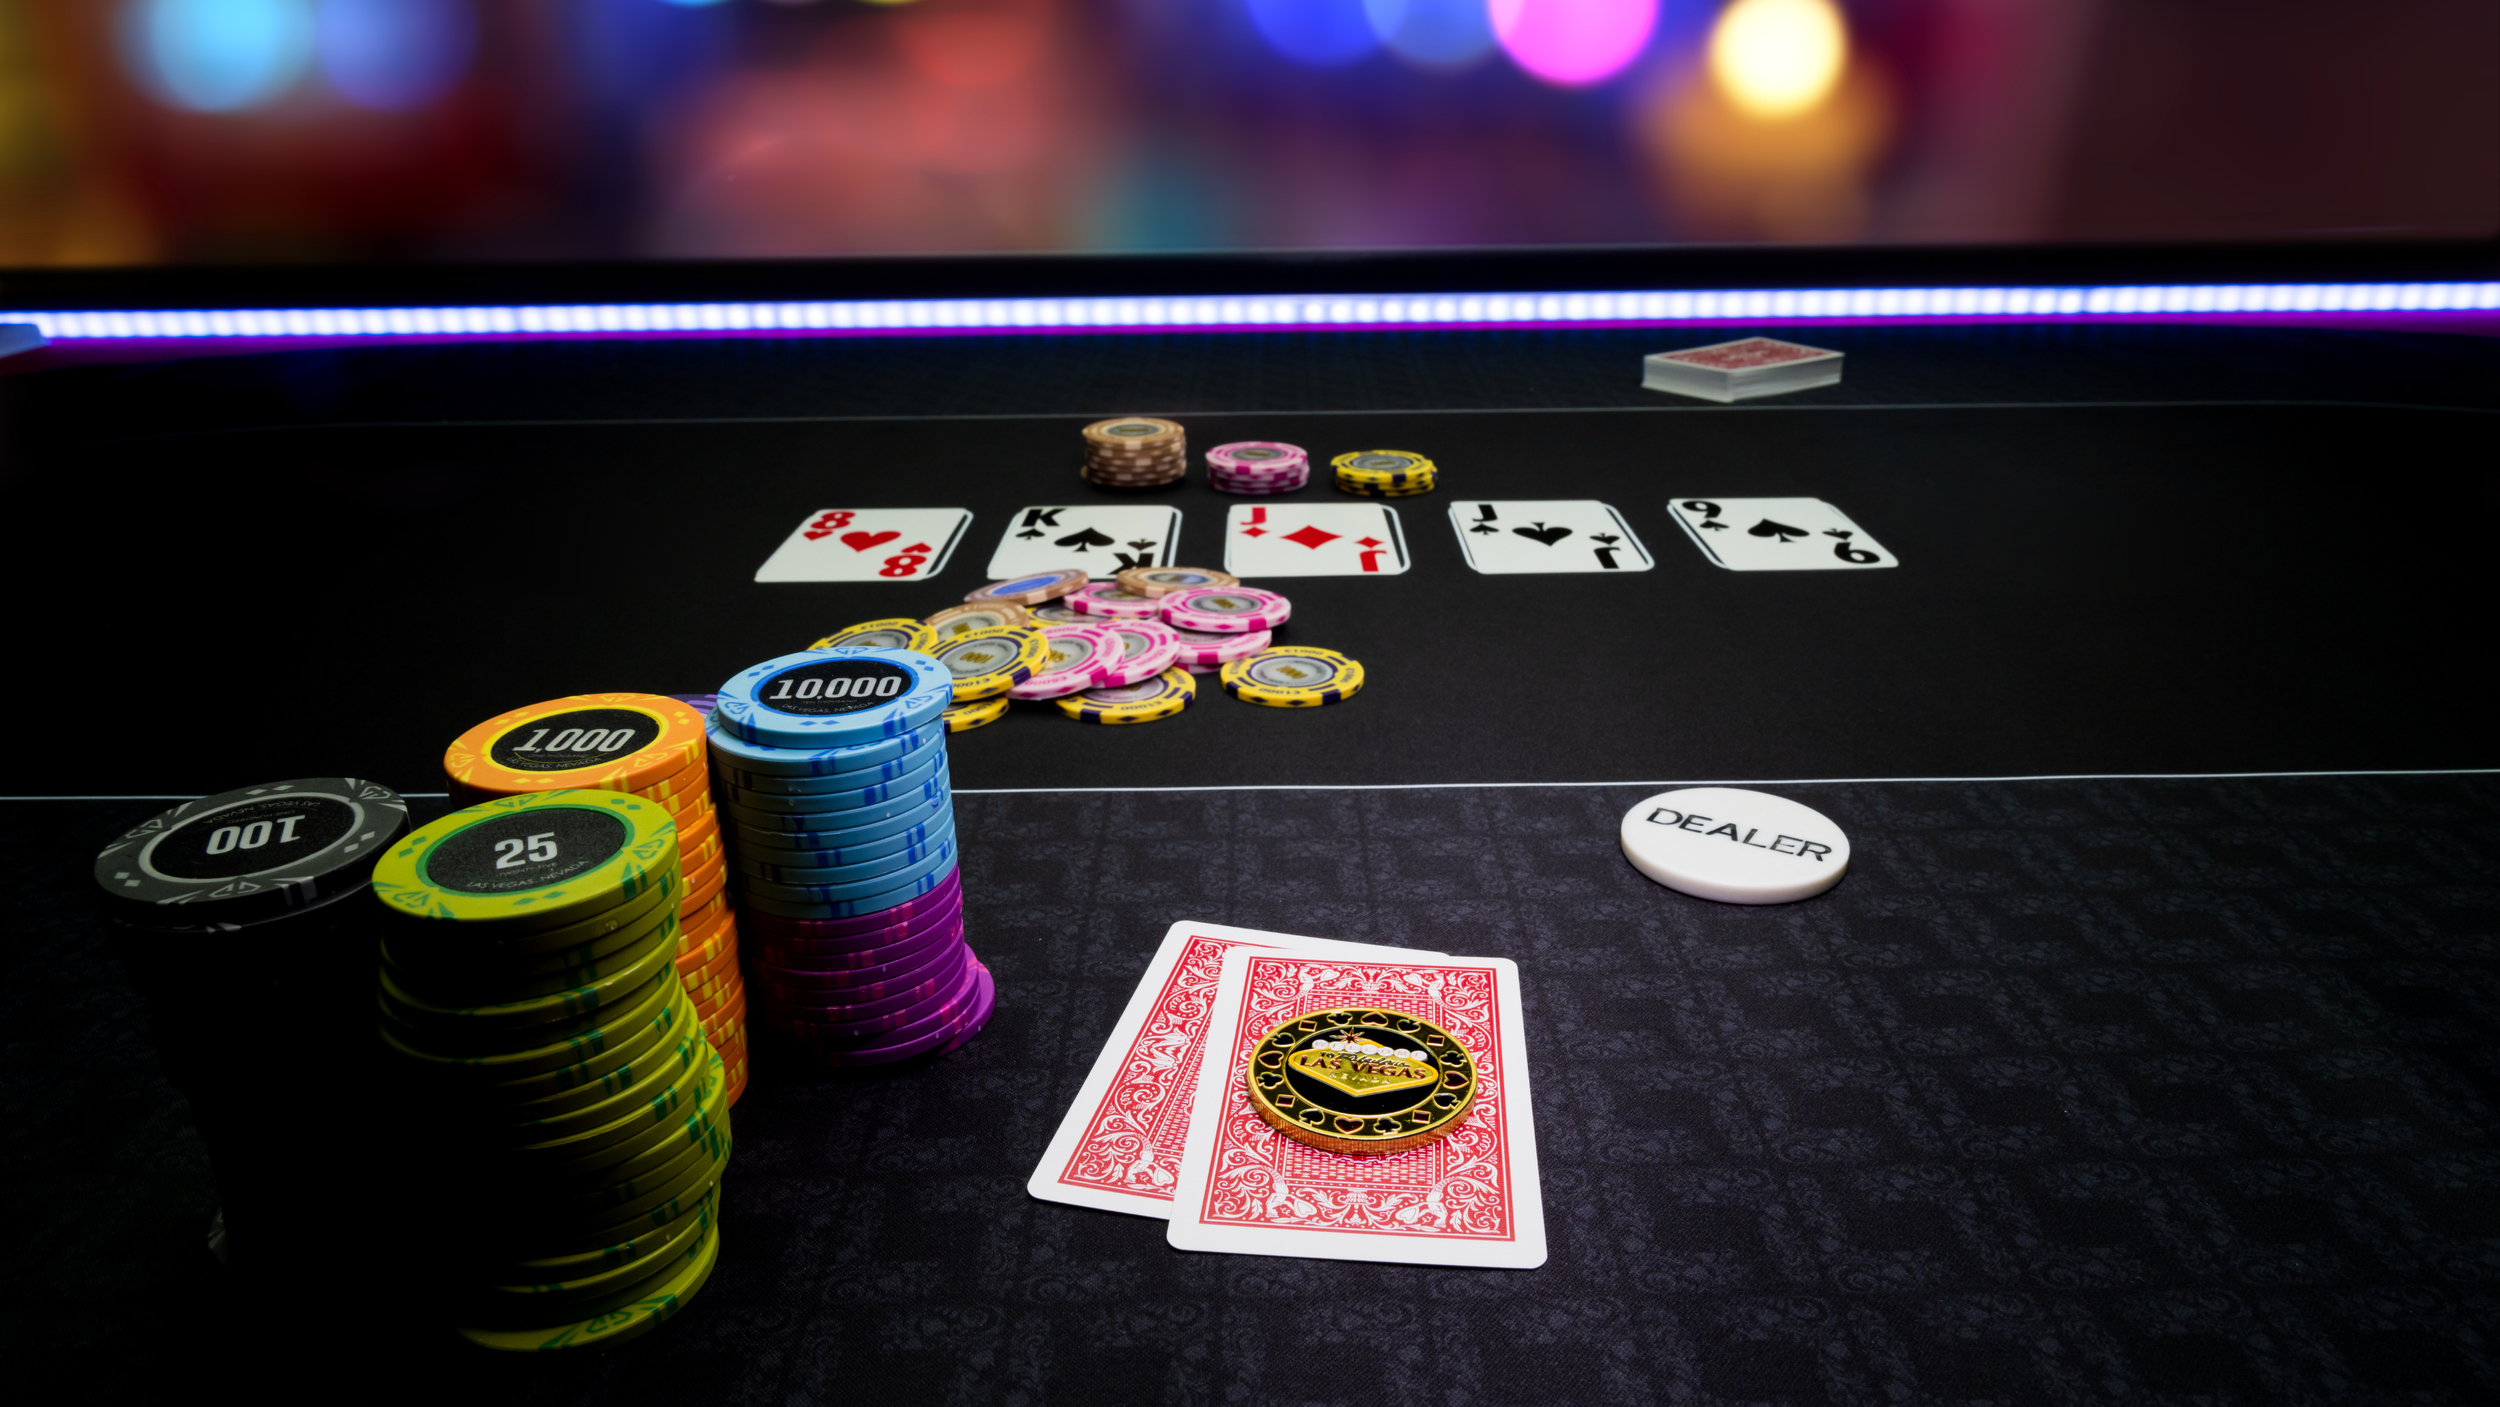
Len: What amazes me when I talk with other families is how consistently they invest in what they understand. I play a lot of poker, and our family enjoys a night at the casino. Watch any blackjack table long enough and you see the same pattern: the more someone plays a game—and the better they know its rules—the bigger they tend to bet. Familiarity feels like an edge, even when the cards don't care.
Psychologists have a name for the trait behind this: desire for control, or DC. In a 1986 study in the Journal of Research in Personality, Santa Clara University psychologist Jerry M. Burger found that high-DC college students bet significantly more than low-DC students when playing with familiar cards, but the gap disappeared when the cards were unfamiliar (Burger, 1986). Same odds, bigger bets—simply because the deck felt familiar.
Adam: Family offices are full of high-DC people. They built their wealth by being in control. So it's no surprise that the portfolio often resembles the founder's résumé: the real estate developer owns more buildings; the operator buys more companies. That instinct helped create the wealth. It isn't necessarily the same instinct that should allocate it.
We're guilty of it too
Len: I'd be pretending if I said we're immune. Given my background, I invest mainly in credit because we're credit managers and that's the game we've played for decades. We know how a loan document reads, where the covenants bite and what a workout looks like. That's our familiar deck.
As we've moved some of our assets out of the company we built and into more liquid investments, we've gradually increased our allocation to two areas outside that comfort zone: venture—which is admittedly more exciting to talk about at dinner—and lower middle market private equity.
Adam: The shift has been deliberate, not a sudden reinvention. Credit remains the core. But concentration in what you know best is still concentration, and part of my job is pushing us to size the bets we're less comfortable with—not just the ones we're good at.
Everyone else is sitting at the same two tables
Len: In talking with other families, what jumps out is how little sits in credit—roughly 3% of assets—while real estate and private equity dominate. The data backs up the anecdotes. UBS's 2025 Global Family Office Report found that alternatives make up 54% of U.S. family office portfolios, with 27% in private equity, 18% in real estate and just 3% in private debt (UBS via WealthBriefing). The 2026 edition still puts private credit at about 3% of the typical family office portfolio (Modus).
That concentration has consequences. Private equity is living through a DPI drought. Bain & Company reports that distributions to LPs as a share of NAV were stuck at 14% in 2025—a level last seen during the 2008–09 financial crisis—and have remained below 15% for four straight years, an industry record (Bain, Global PE Report 2026). By Bain's midyear 2026 count, the industry was sitting on roughly 33,000 unsold portfolio companies (Bain, Midyear 2026). Families that went heavy on PE are waiting longer for capital to come back. In that environment, a contractual coupon can look especially attractive.
Adam: Our portfolio is almost the mirror image, with the majority of our alternatives exposure in private credit rather than other asset classes. The appeal is straightforward: you get paid to wait.
What we give up, however, is the upside of ownership: equity compounding in a lower middle market business we help grow; the power-law potential in venture, where one company can return an entire fund; and the inflation protection and depreciation benefits of real estate. There's a tax tradeoff too. Credit income is generally taxed as ordinary income each year unless held in a tax-advantaged structure, while equity gains can compound until exit and may qualify for long-term capital-gains treatment. A portfolio built entirely on coupons can be steady, but it may not capture the same long-term upside as ownership assets.
Play more than one table
Len: The encouraging part is that families are increasingly recognizing that at least some portion of their assets may belong in each major asset class—not because every category will win every year, but because the one you know best will eventually have a bad hand. In 2026, 60% of family offices told UBS they planned to change their strategic asset allocation over the next 12 months, the highest share UBS has recorded (UBS, Global Family Office Report 2026).
Adam: Our takeaway is simple: know your DC. Lean into your edge, but put a floor under the categories you'd naturally ignore—whether that's credit for a family that made its money in real estate, or venture and lower middle market PE for credit people like us. Diversifying doesn't mean pretending you suddenly have an edge in a game you've never played.
When we step into an asset class where we're not the experts, we look for a family that is: one that has built and operated real estate for three generations, for example, or one that made its fortune running businesses in a particular sector. Investing alongside them can give us access to their deal flow, underwriting experience and judgment. In the right partnership, that can be more compelling than simply hiring a sponsor or asset manager, because the family is investing from its own balance sheet, on its own timeline, with its reputation attached. The alignment is tangible.
At the poker table, the best players aren't the ones who play only the hands they like. They recognize when the deck has changed—and they know who at the table reads it better than they do.
Our Table: The Private Credit Opportunity
Len: Right now, between the macro backdrop and the changes happening inside private credit itself, more families in our network are calling us. After years of strong inflows, the industry is being tested. In the first quarter of 2026, non-traded BDCs met roughly $6.9 billion in redemption requests while raising about $4.9 billion, meaning redemptions exceeded new fundraising (Robert A. Stanger & Co. via HedgeCo). New direct-lending volume fell about 40% in the three months through May (PitchBook via ECM Source). When the game changes, people call the players who've been at that table for decades.
Adam: The stress can also create opportunity. On the deals getting done today, lenders are earning wider spreads, with lower leverage and more lender-friendly documentation than a year ago (ECM Source). The families leaning on us for expertise want exposure to that repricing without the problems they're reading about: liquidity terms they can understand, transparency into the portfolio and a manager whose interests are aligned with theirs.
So we structured a fully aligned way to collaborate: the Founders Round of TCG Specialty Lending. We invest alongside our partners, and Founders Round investors share in ownership of the adviser itself—creating a structure designed to align our economics with theirs.
Len: The Founders Round is our invitation to other families to sit at our table.
Sources
UBS Global Family Office Report 2025, via WealthBriefing
UBS Global Family Office Report 2025, via Truehouse Partners
UBS Global Family Office Report 2026, press release
UBS Global Family Office Report 2026, via Modus
Bain & Company, Global Private Equity Report 2026
Bain & Company, 2026 Midyear PE Report
Cliffwater Report on US Direct Lending (through Dec 2023)
Robert A. Stanger & Co., Q1 2026 non-listed BDC fundraising, via HedgeCo
PitchBook US Private Credit Monitor, May 2026, via ECM Source
Len Tannenbaum
Founder
Tannenbaum Capital Group
Adam Tannenbaum
Co-Founder
Tannenbaum Capital Group
We Are Credit Investors—With You and For You
Tannenbaum Capital Group refers to a group of affiliated asset managers (each a “TCG entity,” and collectively, “TCG”) committed to delivering innovative capital solutions to institutions, family offices, and individual investors. Each TCG entity specializes in a credit-based strategy, which include real estate lending, and private credit, all focused on generating strong risk-adjusted returns and preserving capital.
Every TCG entity is led by a seasoned team with deep industry expertise. The management personnel of TCG are collectively the largest group of shareholders in every product TCG offers, ensuring meaningful alignment with the interests of all shareholders.
This level of alignment and ownership is a core principle that sets TCG apart.