By James Zimbardi & Larry McKay, CFA, CTFA
The Diversification Illusion
Ten companies now make up roughly 35% of the S&P 500. They trade at about 50 times forward earnings, while the median for the other 490 sits near 16, according to Apollo's January 2026 analysis. If you own the index, you own a concentrated bet that happens to wear a diversified label.
Most investors we speak with fall into one of two camps. The first is heavily overweight megacaps, often without meaning to be, through index funds, growth managers and direct holdings that all point back to the same handful of names. The second owns smaller, less familiar companies but holds them the way you might hold a lottery ticket: small positions, a thin thesis, and a quick exit at the first drawdown.
Neither camp has what matters most in a crowded market. That is conviction in something the consensus has not yet priced.
Our view is simple. The next decade of technology returns will come less from the companies building AI and more from the companies AI cannot scale without. Every big story has a choke point, and choke points are where scarcity, pricing power and mispricing tend to live.
Two themes make the case vividly. Humanoid robotics, which we believe reaches a commercial inflection in 2027, and energy efficiency, the slower but far larger contest to power everything AI wants to do.
Follow the Bottleneck, Not the Headline
Headlines follow the companies that sell the finished product. Returns often follow the companies that sell the scarce input. During the dot-com buildout, the network was the story. Today, the large language model is the story. In both cases, the parts that could not be produced fast enough held real pricing power.
The opportunity set has also moved. The number of U.S. listed companies fell from just over 8,000 in 1996 to roughly 4,600 by 2022, according to Sherwood News. Many of the most interesting builders now stay private far longer. That means a portfolio limited to public markets sees only part of the picture, and a portfolio limited to megacaps sees even less.
We use a simple screen to find bottlenecks worth owning:
Scarcity: demand is growing faster than capacity can be added, often because of specialized materials, skills or permits.
Specificity: the input is hard to substitute, so customers pay for reliability rather than shop on price.
Neglect: sell-side coverage is thin, and the company rarely appears in thematic ETFs.
Access: the exposure can be owned through public small and mid caps, private rounds, or both.
"Concentration is not the same as conviction. Owning what everyone owns is a decision too, just an unexamined one."
Run that screen across today's AI economy and two areas keep surfacing.
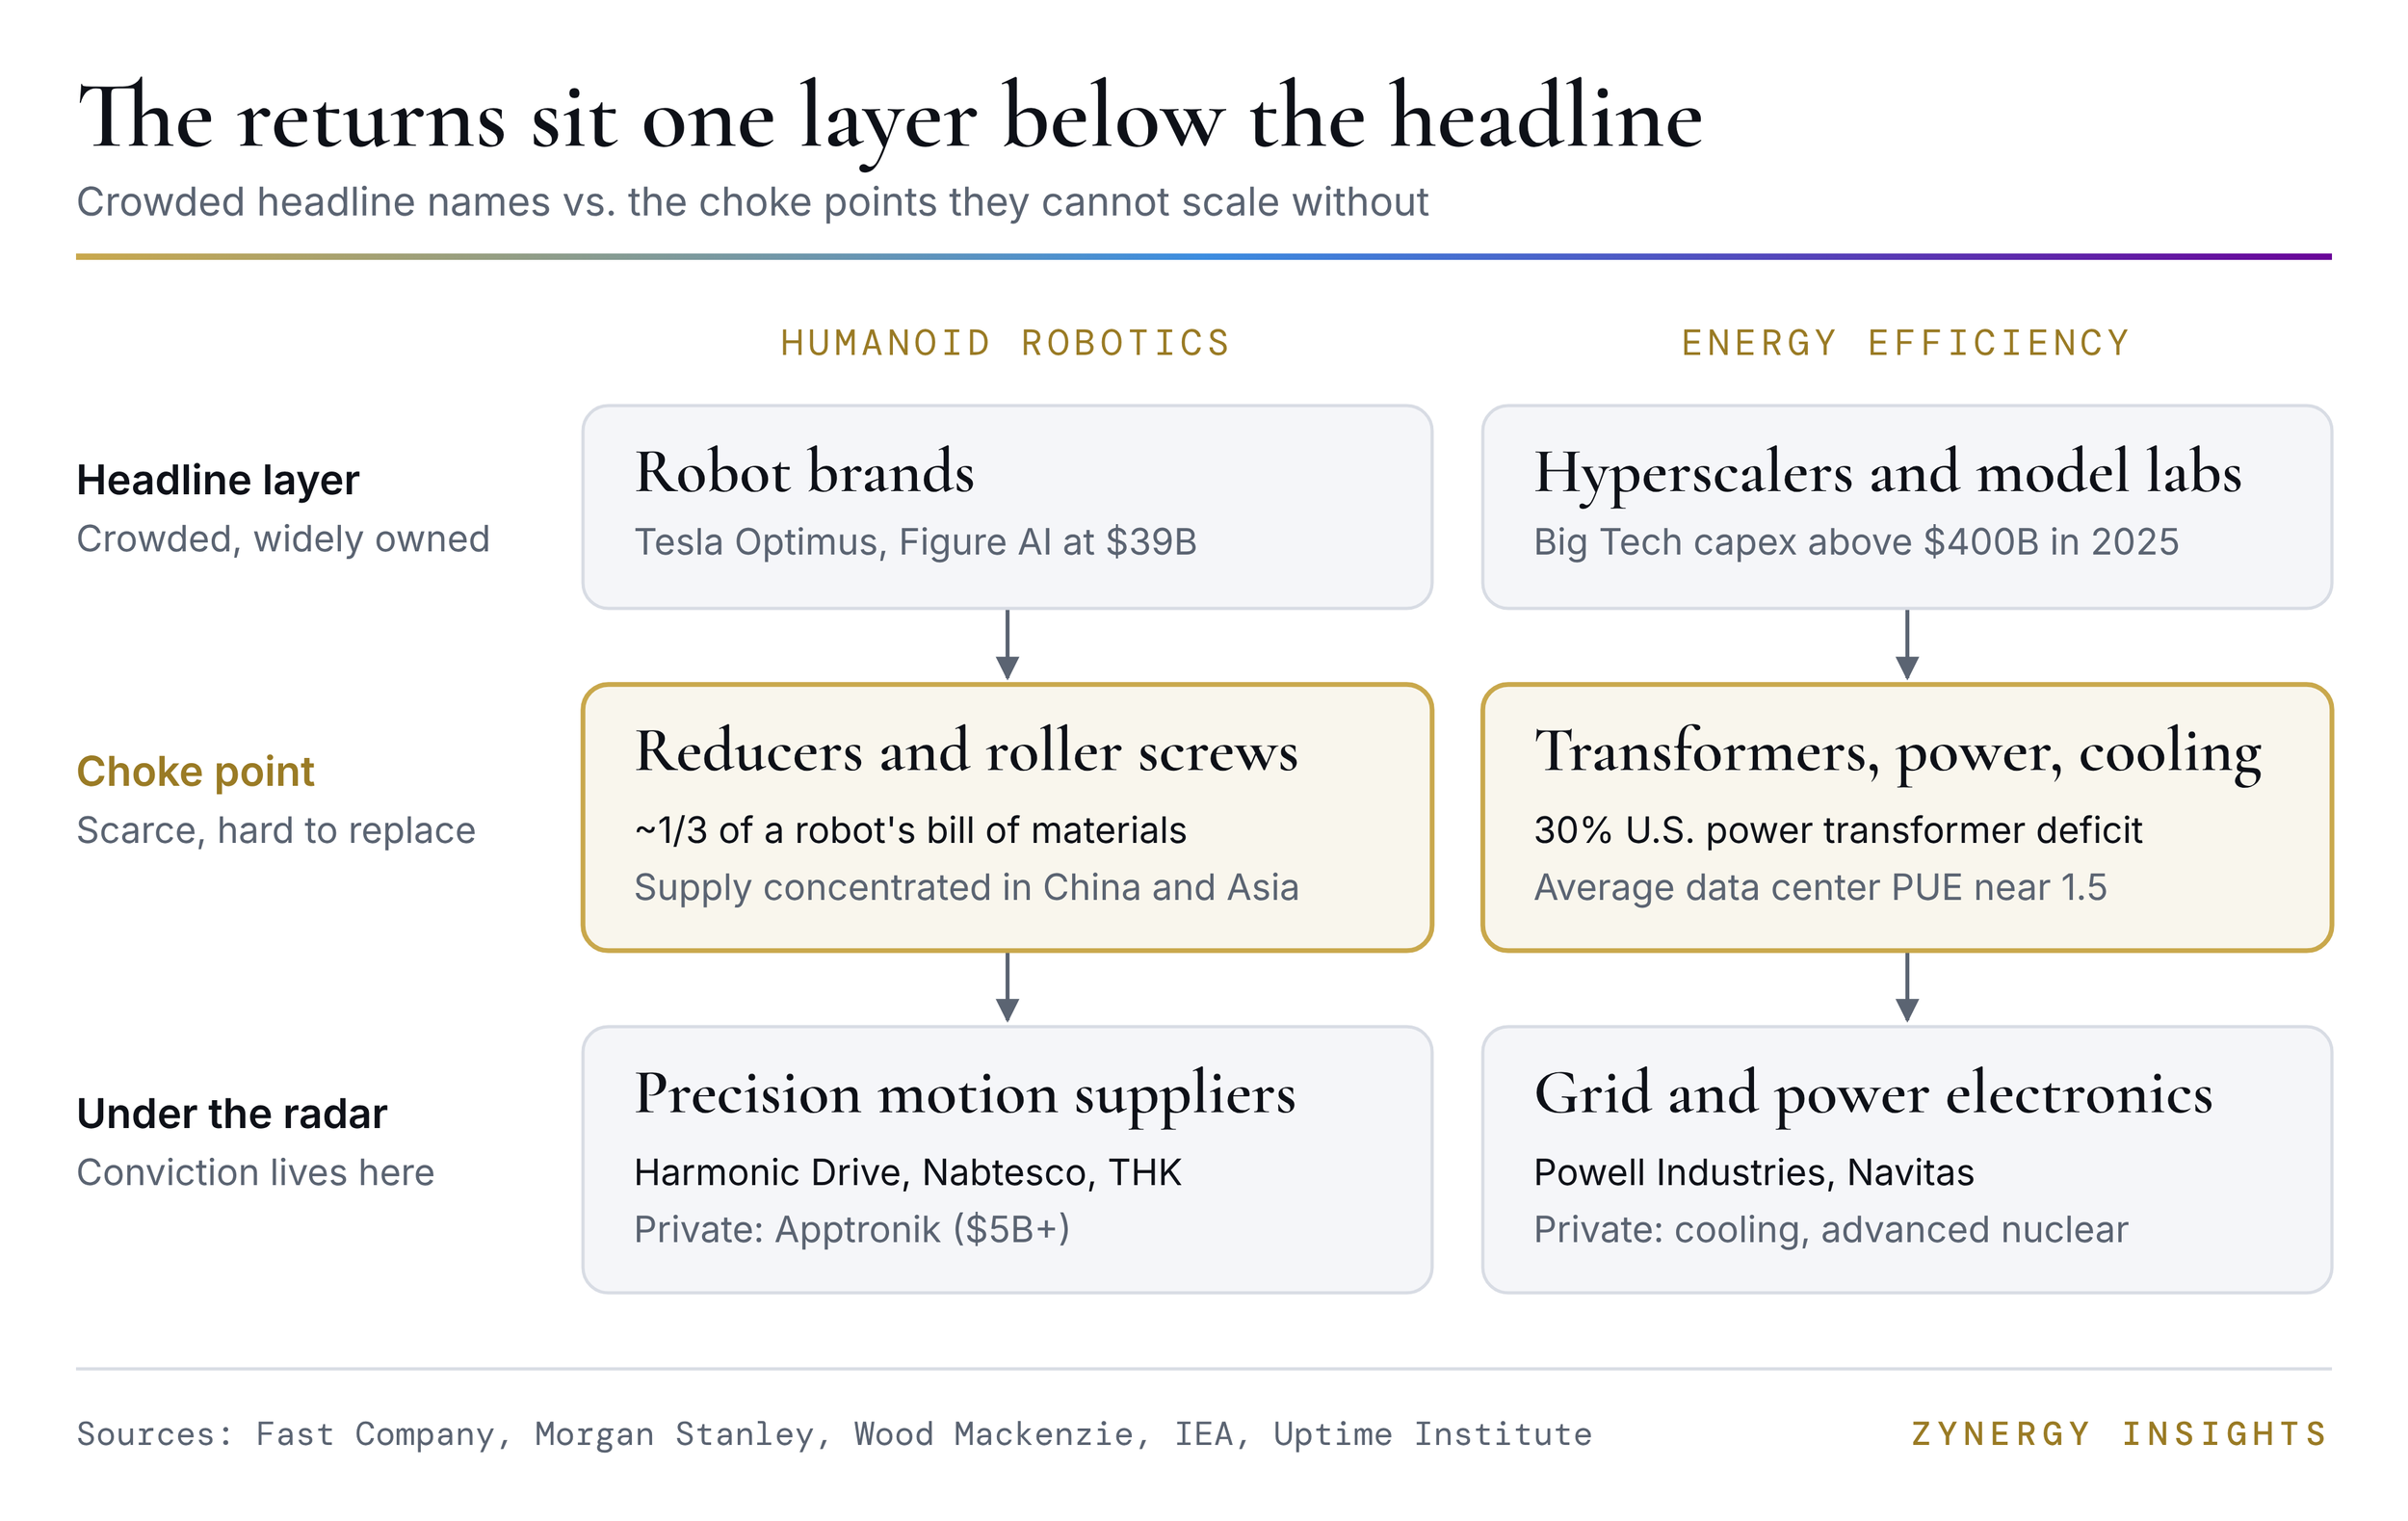
Exhibit 1 · The Bottleneck Map · names are illustrative, not recommendations
Theme 1: Humanoids in 2027, and Why the Money Is in the Joints
Why 2027 matters
Forecasts for humanoid robots are rising quickly. In September 2026, Goldman Sachs raised its 2030 shipment estimate to 890,000 units from 256,000, and now expects 6.5 million units a year by 2035, a market of roughly $138 billion (24/7 Wall St.). Over a longer horizon, Morgan Stanley's Adam Jonas sees more than 1 billion humanoids in use by 2050, supporting a $5 trillion market (Morgan Stanley).
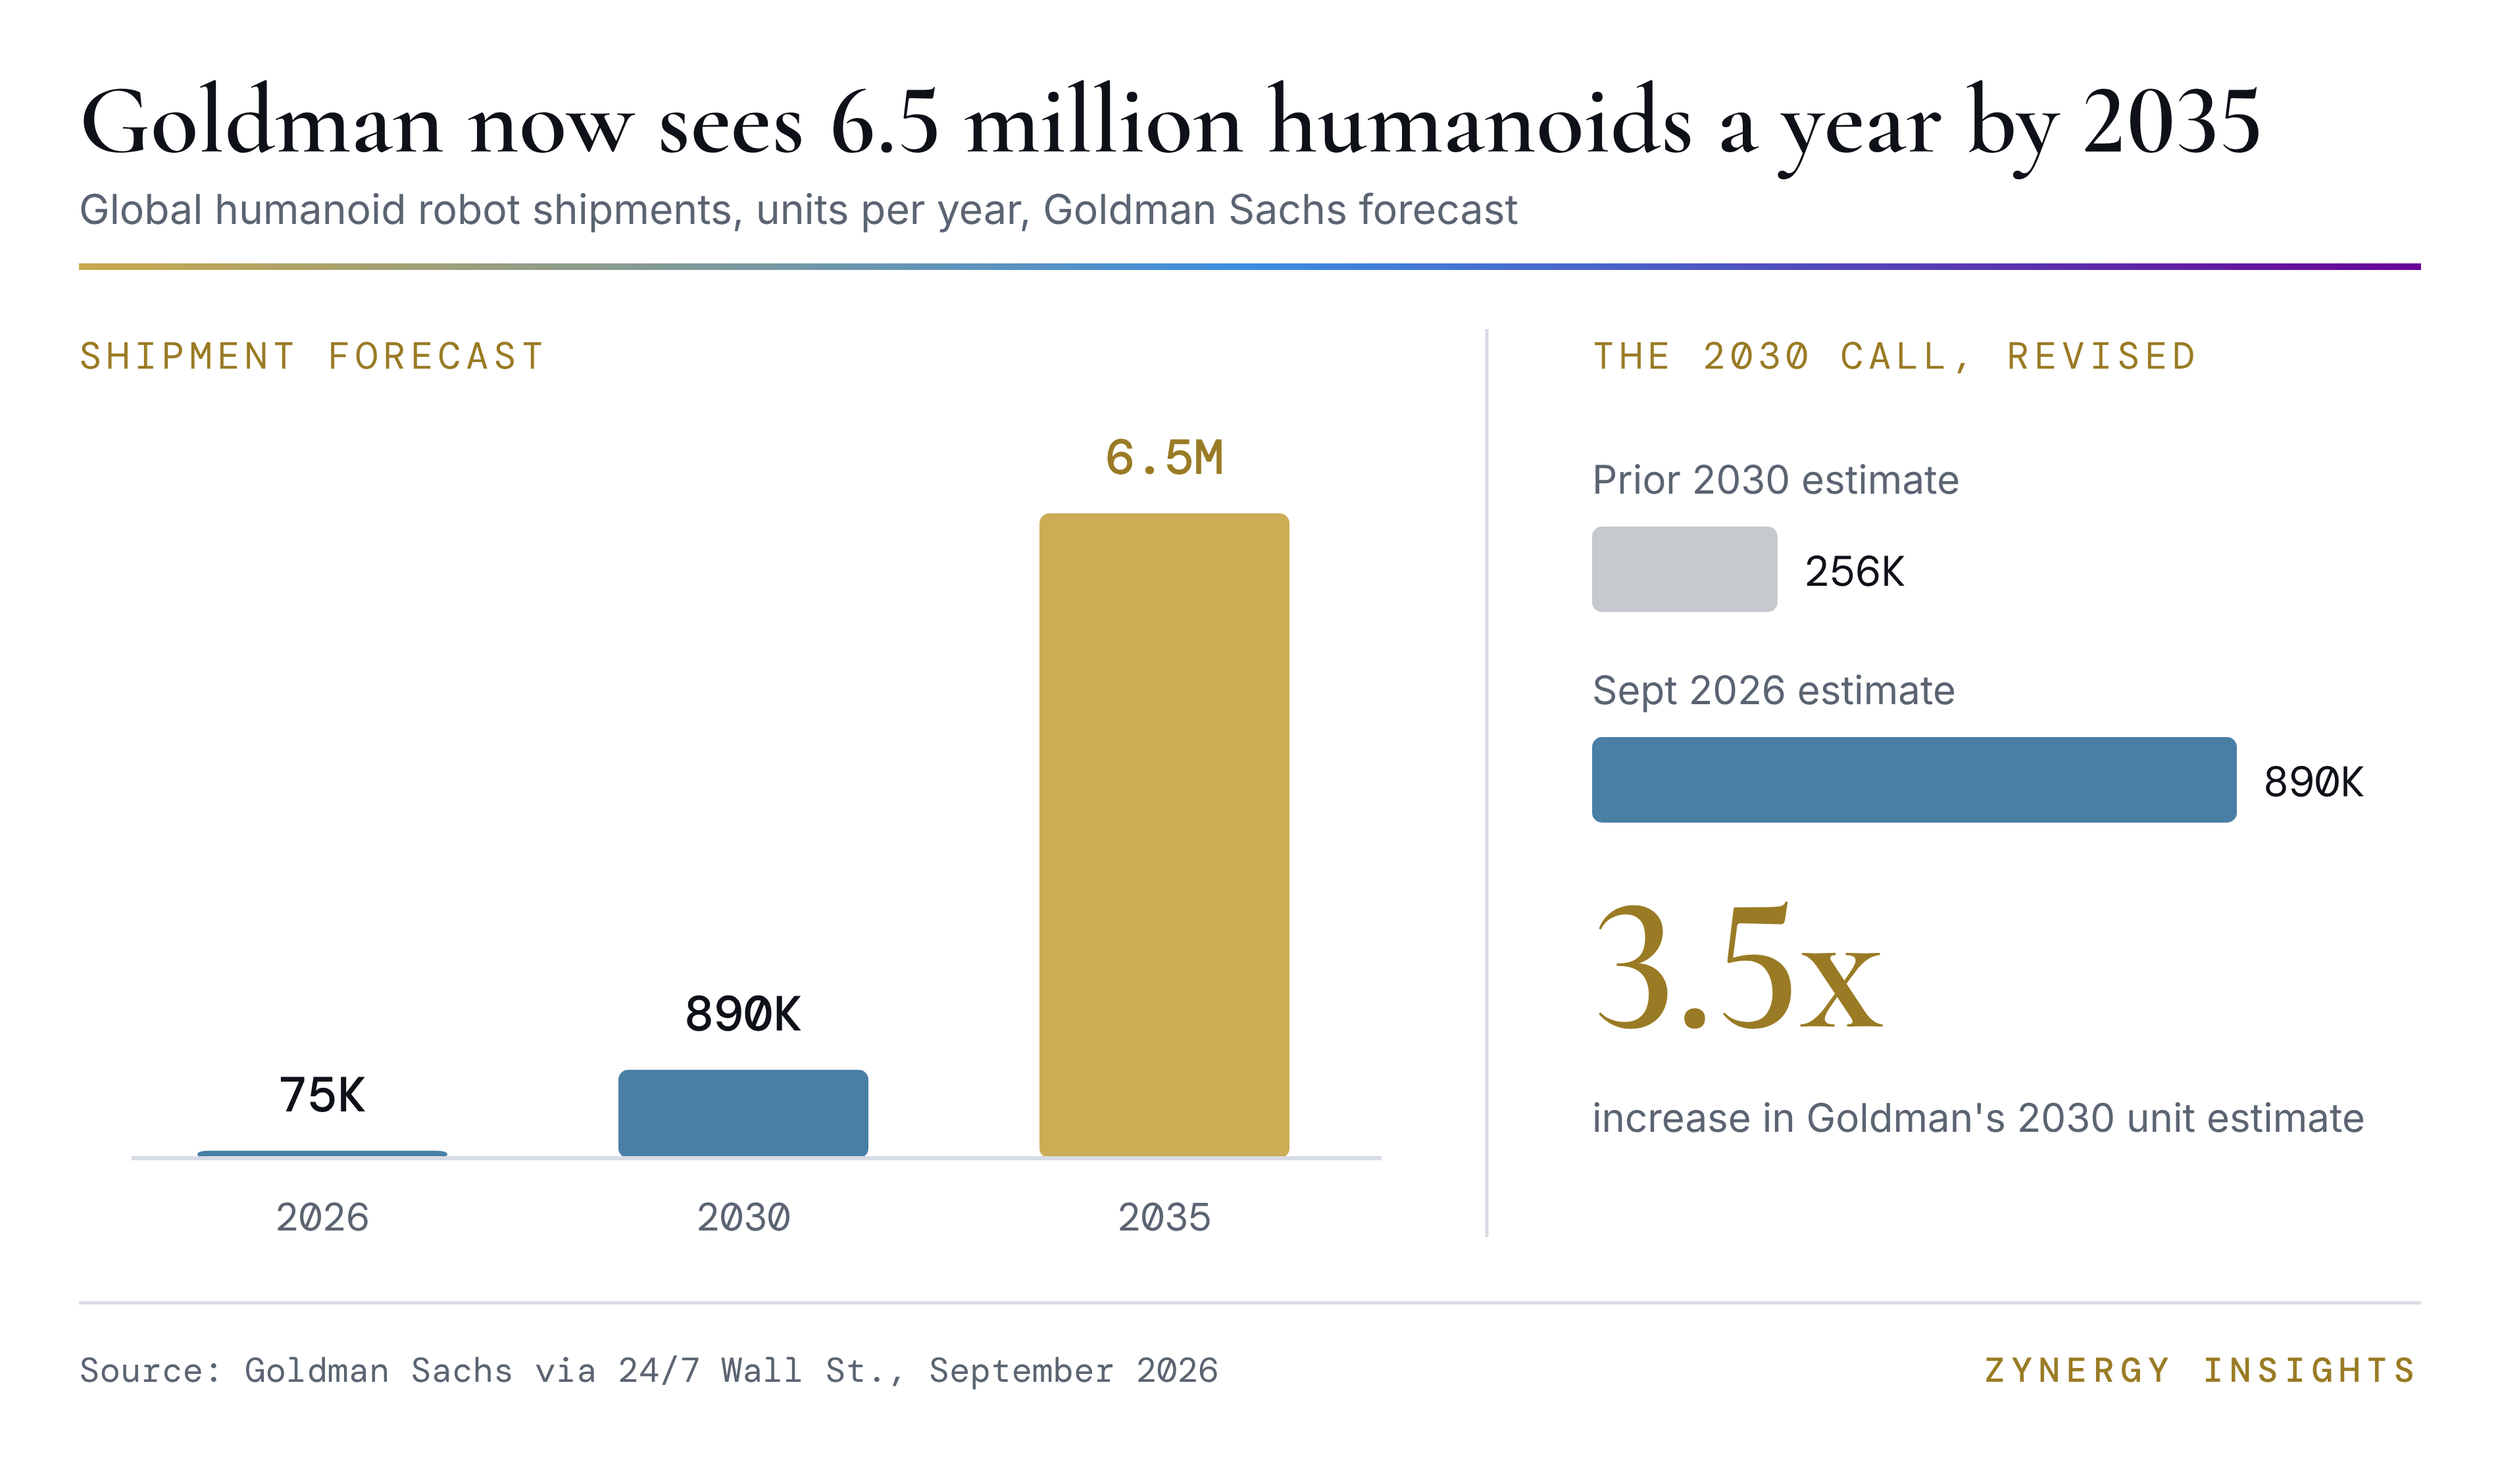
Exhibit 2 · Goldman Sachs humanoid forecast, Sept 2026 · via 24/7 Wall St.
The economics are already shifting. China's Unitree sold 5,500 humanoids in 2025, roughly a third of global sales, while its average selling price fell from about $85,000 in 2023 to about $25,000. It still earned gross margins near 60% (Rest of World). Private capital has noticed too. Venture funding for humanoids jumped from $1.5 billion in 2024 to $6.1 billion in 2025, according to PitchBook.
We see 2027 as the year pilots become purchase orders. Units are moving from the hundreds to the tens of thousands, and that is the point where supply chains, not demos, decide who wins.
The choke point is the joint
A humanoid needs 40 or more actuators. Reducers and planetary roller screws, the precision parts that turn motor spin into controlled movement, make up roughly a third of a robot's bill of materials, according to Fast Company. A single roller screw can cost $1,350 to $2,700. Morgan Stanley adds that nearly all robot developers still source these critical parts from China and Asia.
That combination of high cost, tight tolerances and concentrated supply is the definition of a bottleneck. It is also where the market is slowly paying attention. Japan's Harmonic Drive Systems, a leader in strain wave gearing, reported orders up 55.7% year over year in its August 2026 quarter, including about ¥1.2 billion in AI robot orders from a North American customer, and raised its operating profit forecast to ¥8.5 billion from ¥6.2 billion (BigGo Finance).
Where conviction can live
Public components: precision reducer and motion-control makers such as Harmonic Drive Systems, Nabtesco and THK, which sell to every robot builder rather than betting on one.
Test and automation: companies like Teradyne, whose robotics and test units benefit as volumes scale.
Private builders: Apptronik raised $520 million at a valuation above $5 billion, backed by Google, Mercedes-Benz and John Deere. Compare that with Figure AI at $39 billion. Both may succeed, but one valuation already prices in much more of the future.
"In a gold rush, the robot gets the headline. The gearbox gets the margin."
Theme 2: Energy Efficiency, Where the Watt Becomes the Unit of Value
The math has changed
Anthropic CEO Dario Amodei has described advanced AI as "a country of geniuses in a datacenter" (Machines of Loving Grace). Countries need power. The International Energy Agency estimates data centers used about 415 terawatt-hours in 2024 and will use around 945 TWh by 2030, slightly more than Japan consumes today (IEA).
The pace is faster than many expected. Data center electricity demand rose 17% in 2025, while global demand grew just 3%. The five largest tech companies spent more than $400 billion on capital expenditure in 2025, and that figure is projected to rise another 75% in 2026 (IEA, April 2026).
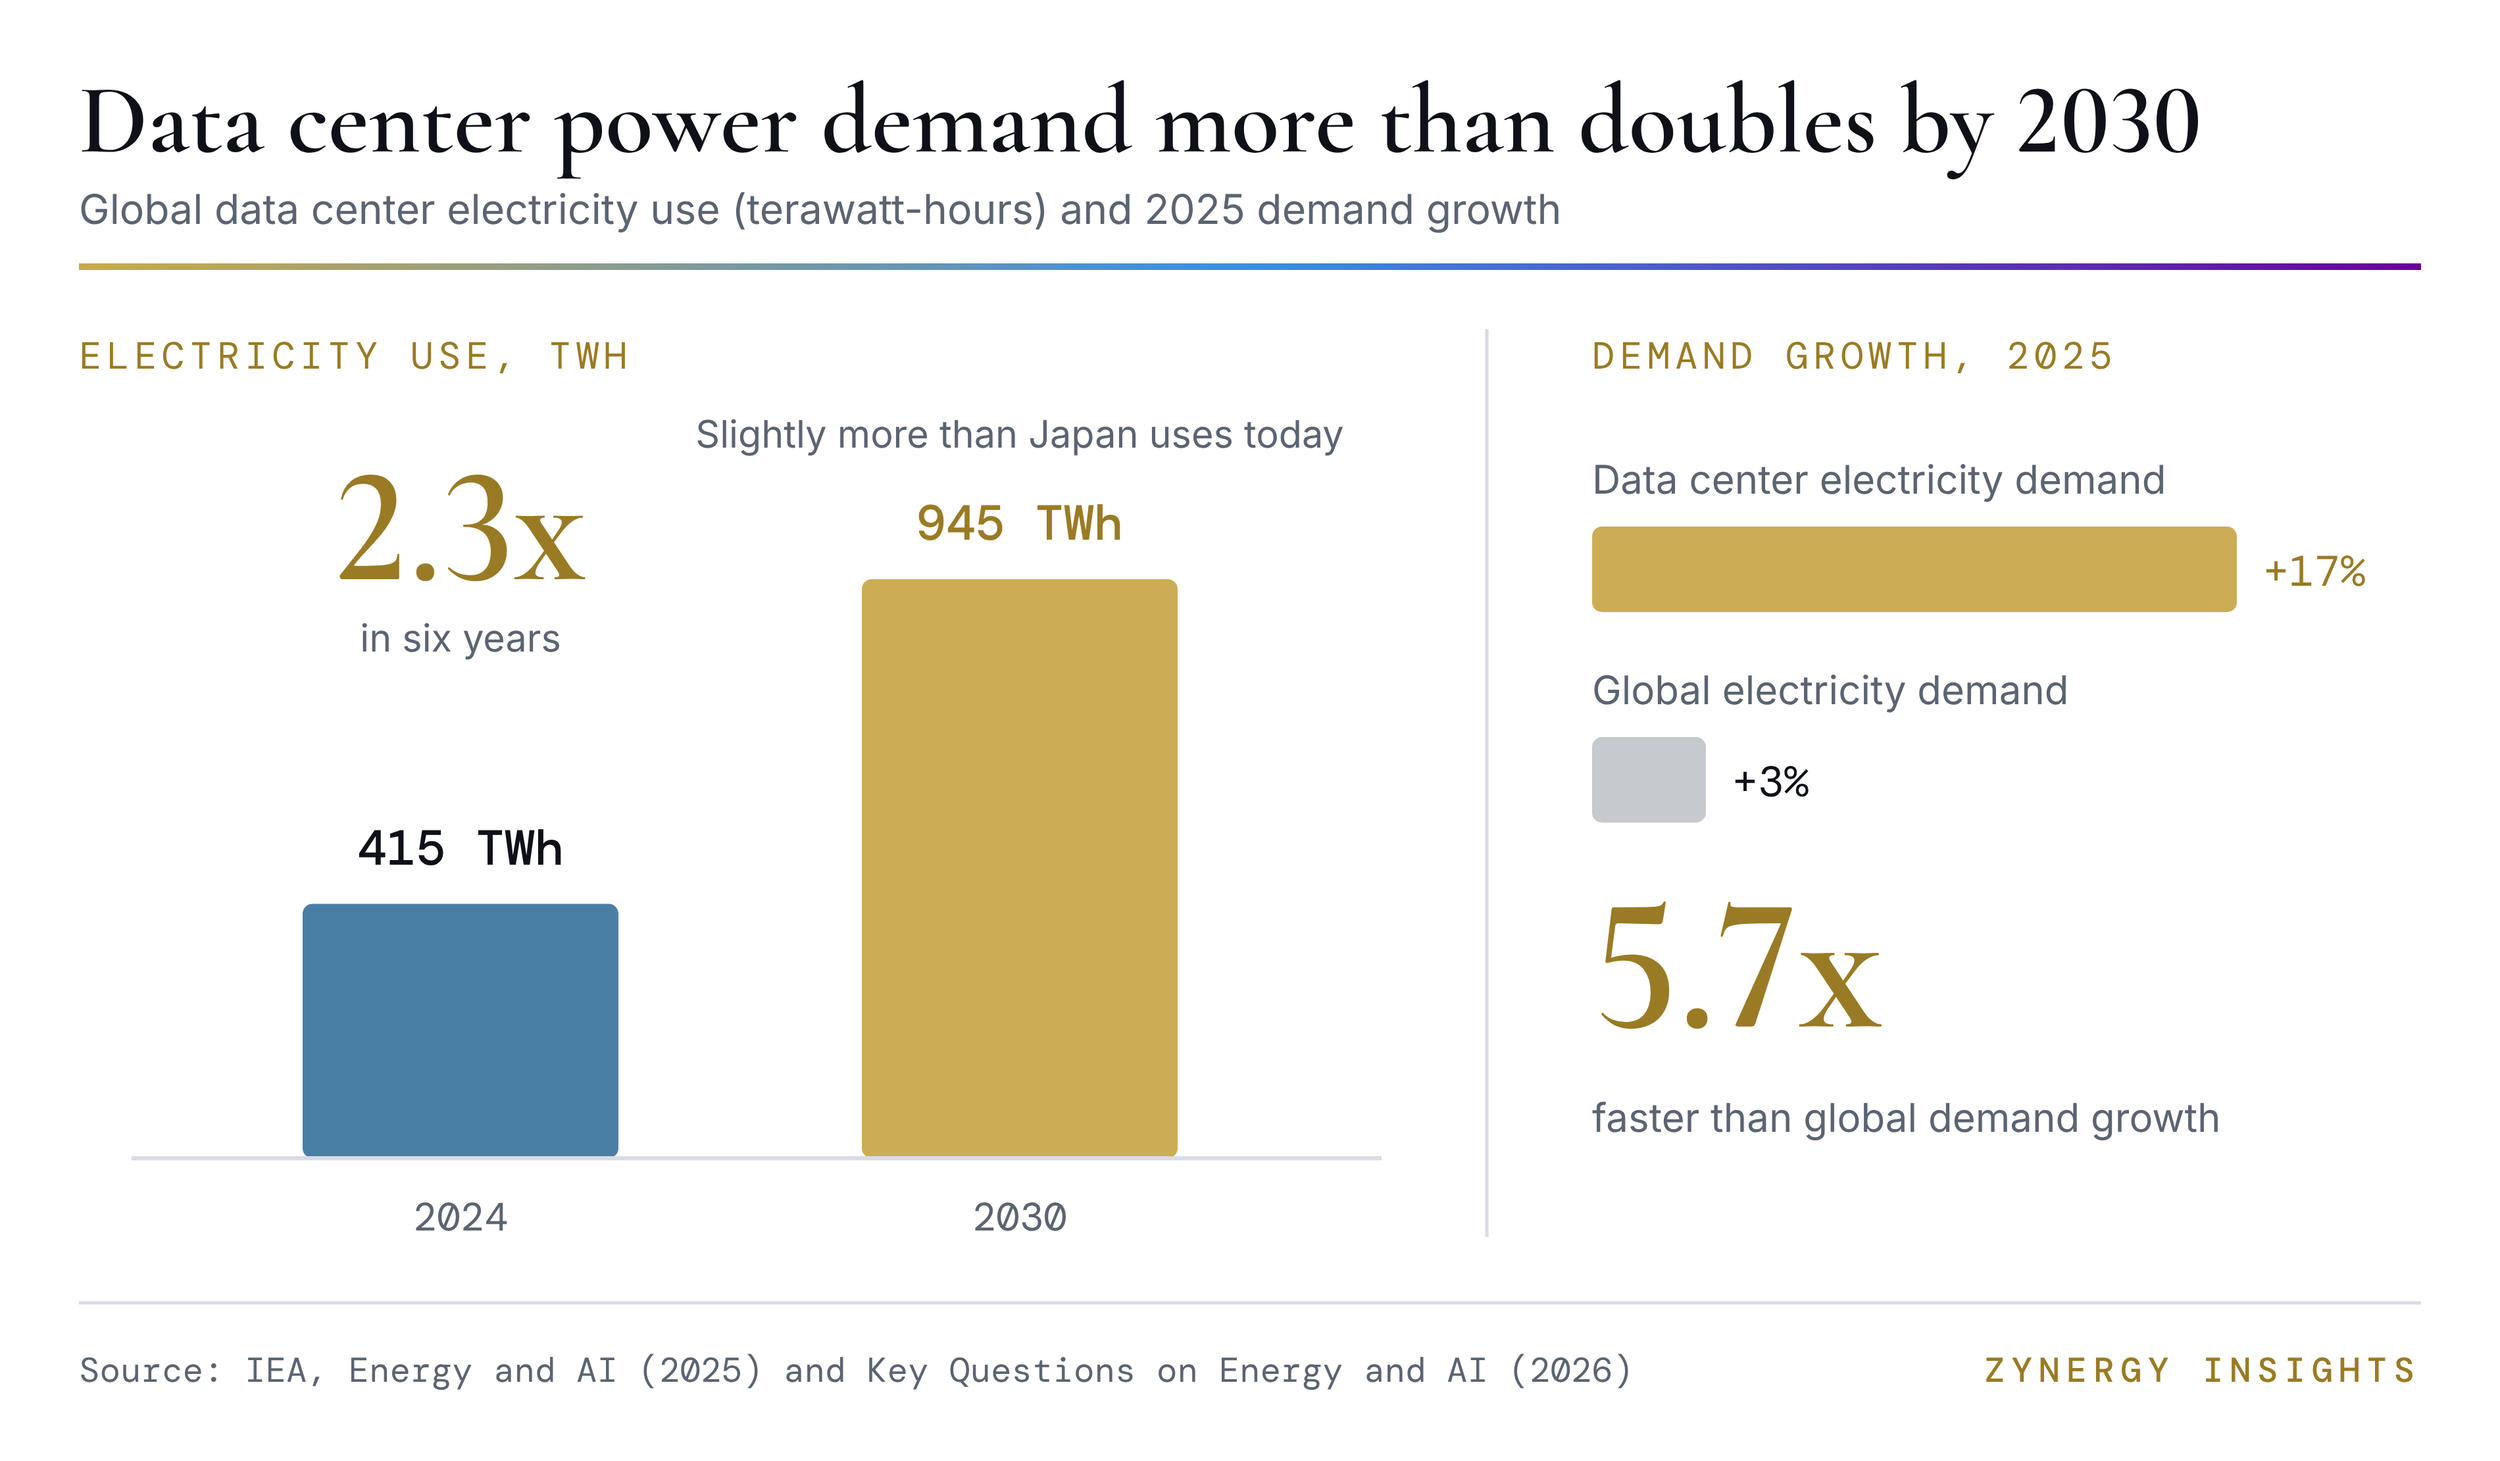
Exhibit 3 · IEA data center electricity, 2024 and 2030 projection; growth in 2025
The choke points
Transformers: the U.S. faces a 30% supply deficit in power transformers, prices are up 77% since 2019, and about 80% of supply is imported (Wood Mackenzie).
Overhead: the average data center still runs a power usage effectiveness near 1.5, which means roughly 50 cents of overhead for cooling and conversion on every dollar of compute power. Leading hyperscalers operate near 1.1 (mGrid, citing Uptime Institute).
Firm power: the small modular reactor pipeline grew from 25 gigawatts at the end of 2024 to 45 GW, according to the IEA.
Where conviction can live
Grid and switchgear specialists: Powell Industries, a Houston maker of electrical distribution equipment, reported a record $1.8 billion backlog in fiscal Q2 2026 (Jan to Mar 2026), with orders up 97%, followed by a data center order above $400 million, the largest in its history (GlobeNewswire).
Power semiconductors: gallium nitride and silicon carbide suppliers such as Navitas, which NVIDIA selected to help develop its 800-volt power architecture for AI data centers.
Cooling and private innovators: liquid cooling, heat reuse and advanced nuclear developers, many of which are still private and reachable only through direct or co-investment rounds.
"In a power-constrained economy, the cheapest megawatt is the one you never have to build."
Turning Low Conviction into High Conviction
Owning an obscure name is easy. Owning it with enough confidence to hold through volatility is the hard part. Here is how we approach it:
Map the bottleneck first, then the company. Start with the scarce input and work outward to who controls it. The ticker is the last step, not the first.
Own the toll road, not the race car. Component and infrastructure suppliers sell to every competitor, so you do not need to pick the winning robot or the winning model.
Pair public liquidity with private access. Listed small and mid caps give you flexibility. Private rounds give you earlier entry into companies that may not list for years.
Size by conviction, not by familiarity. A position you have researched deeply deserves more weight than one you know only by its brand.
Set the disconfirming evidence in advance. Write down what would prove the thesis wrong, such as pricing pressure, a cheaper substitute or a policy shift, and revisit it every quarter.
The risks are real. Harmonic Drive's own management has warned that pricing "will be somewhat challenging going forward" as robot volumes rise. Morgan Stanley expects humanoid adoption to stay "relatively slow until the mid-2030s." Supply chains concentrated in China carry trade and policy risk. Conviction is not certainty. It is a clear thesis paired with a disciplined plan for being wrong.
What It Means for You
The index will keep rewarding the megacaps until it doesn't. We are not suggesting you abandon them. We are suggesting you stop mistaking them for diversification, and stop treating your smaller positions as afterthoughts.
The humanoid buildout and the race for energy efficiency are two of the clearest places where scarcity, neglect and long-term demand meet. The companies sitting at those choke points are rarely household names. That is exactly why they deserve a closer look.
Connect with the Zynergy team to explore how our research-driven approach to public and private innovation can bring uncorrelated conviction to your portfolio.
This article is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Companies named are illustrative examples. Zynergy Investments and its affiliates may hold positions in securities discussed.
Sources
James Zimbardi
Chief Executive Officer
Zynergy
Larry McKay, CFA, CTFA
Chief Investment Officer - CIO
Zynergy
Zynergy is an AI-focused private investment firm providing differentiated access to public and private technology opportunities. Led by MIT-trained investment professionals, Zynergy combines an actively managed Technology & AI Investment Fund with a Digital AI Lab that incubates and accelerates breakthrough technology companies.
We partner with accredited investors, family offices, and sophisticated executives seeking high-conviction exposure to the innovation economy through a disciplined, research-driven investment approach. Our philosophy is grounded in the belief that technological innovation is the most powerful driver of long-term economic growth and value creation. By identifying emerging technologies, underfollowed companies, and visionary founders before they become broadly recognized, we seek to generate attractive risk-adjusted returns while providing differentiated exposure beyond traditional investment strategies.